First-Time Home Buyer Victoria BC: 2026 Guide
October 8, 2026
First-Time Home Buyer Victoria: Programs, Rebates, Taxes & Costs Explained (2026)
Buying your first home in Victoria, BC, comes with more than just a down payment. Between property transfer taxes, mortgage requirements, legal fees and closing costs, understanding the full financial picture can make a meaningful difference in what you can afford.
The good news? Several provincial and federal programs can help first-time buyers reduce their upfront costs, save for a down payment and potentially recover thousands of dollars in taxes.
Whether you're considering a condo in downtown Victoria, a townhome in Langford or a new development in Colwood, here's what you need to know before making your first purchase.
What programs are available for first-time home buyers in Victoria, BC?
First-time home buyers in Victoria may qualify for property transfer tax exemptions, a new-home GST rebate, tax-advantaged savings accounts and federal home-buying incentives. Eligibility depends on the program, your purchase price, ownership history and whether you're buying a new or resale home.
Program
Potential benefit
BC First Time Home Buyers' Program
Up to $8,000 off property transfer tax
BC Newly Built Home Exemption
Full property transfer tax exemption on qualifying new homes up to $1.1 million
Federal First-Time Home Buyers' GST Rebate
Up to $50,000 in GST relief on qualifying new homes
First Home Savings Account (FHSA)
$8,000 annual contribution room, $40,000 lifetime limit
Home Buyers' Plan (HBP)
Withdraw up to $60,000 from an RRSP, subject to repayment rules
Home Buyers' Amount
Non-refundable federal tax credit worth up to $1,500
These programs have different eligibility requirements. Not every buyer will qualify for every benefit, and some may be used together.
1. BC First Time Home Buyers' Program: How much property transfer tax can you save?
British Columbia's First Time Home Buyers' Program helps eligible purchasers reduce the property transfer tax (PTT) payable when buying their first principal residence.
In 2026, eligible buyers can receive:
A full property transfer tax exemption on homes valued at $500,000 or less.
An $8,000 exemption on homes valued above $500,000 and up to $835,000.
A reduced exemption on homes valued above $835,000 but below $860,000.
At $860,000 or more, the first-time buyer exemption no longer applies. For homes between $500,000 and $835,000, the $8,000 exemption may not eliminate the entire tax bill.
How much property transfer tax would a first-time buyer pay in Victoria?
Purchase price
Regular PTT
PTT after first-time buyer exemption
$450,000
$7,000
$0
$550,000
$9,000
$1,000
$650,000
$11,000
$3,000
$750,000
$13,000
$5,000
$800,000
$14,000
$6,000
$850,000
$15,000
$11,800
These examples assume the entire property qualifies, the buyer meets all program requirements, and no special property conditions apply.
Who qualifies for the BC first-time home buyer exemption?
Eligibility generally requires buyers to meet provincial residency or tax-filing conditions, hold Canadian citizenship or permanent resident status, and satisfy the program's previous ownership rules.
The property must also become the buyer's principal residence. Additional requirements apply to property size, occupancy timing and continued use of the home.
Review the official BC First Time Home Buyers' Program eligibility requirements before relying on the exemption.
2. First-Time Home Buyer GST Rebate: Can you save up to $50,000 on a new home?
Yes. Eligible first-time home buyers can receive a rebate of up to $50,000 in federal GST when purchasing a qualifying newly built or substantially renovated home.
The 2026 federal program provides:
New home purchase price
Potential GST rebate
Up to $1,000,000
Up to 100% of GST, maximum $50,000
$1,000,001 to $1,499,999
Gradually reduced rebate
$1,500,000 or more
No first-time buyer GST rebate
For example, a qualifying $600,000 newly built condo would ordinarily carry $30,000 in GST at the 5% rate. An eligible first-time buyer may receive a rebate covering the full $30,000.
Who qualifies for the new-home GST rebate?
For a typical purchase from a builder, important conditions include:
The buyer must satisfy the federal first-time buyer definition.
The home must be newly constructed or substantially renovated and intended as the buyer's primary residence.
The agreement of purchase and sale must generally have been entered into on or after March 20, 2025, and before 2031.
Additional construction, occupancy and transfer deadlines must be met.
Builders can credit the rebate at closing, or eligible purchasers may apply directly to the Canada Revenue Agency when the builder has not provided the credit. Buyers should confirm whether the advertised purchase price already reflects a rebate.
For buyers comparing resale condos with brand-new developments in the Westshore, this can materially change the total purchase cost.
Explore new residential developments in Greater Victoria to see how new construction compares with resale opportunities.
3. BC Newly Built Home Exemption: Is property transfer tax waived on new homes?
British Columbia also offers a separate property transfer tax exemption for qualifying newly constructed principal residences.
Under the BC Newly Built Home Exemption:
Qualifying new homes valued up to $1.1 million may receive a full property transfer tax exemption.
Homes valued above $1.1 million but below $1.15 million may receive a partial exemption.
The exemption phases out at $1.15 million.
Unlike the BC First Time Home Buyers' Program, this exemption is not restricted exclusively to first-time purchasers.
Can you combine the BC new-home exemption with the federal GST rebate?
Yes, a qualifying first-time buyer may benefit from both the provincial newly built home property transfer tax exemption and the federal first-time buyer GST rebate.
For example, consider an eligible buyer purchasing a newly built $700,000 condo:
Tax or savings
Amount
Standard BC property transfer tax
$12,000
BC newly built home exemption
−$12,000
GST at 5%
$35,000
Eligible federal first-time buyer GST rebate
−$35,000
Combined potential tax savings
$47,000
This example assumes full eligibility for both programs. The buyer would still need to cover the down payment and other closing costs.
The BC first-time buyer and newly built home PTT exemptions are alternative routes to reducing the same provincial tax, not duplicate refunds of it.
4. First Home Savings Account (FHSA): How can it help you buy in Victoria?
The First Home Savings Account is one of the most useful tools available to Canadians preparing to purchase their first home.
An FHSA combines two tax advantages:
Tax-deductible contributions: Eligible contributions reduce your taxable income.
Tax-free qualifying withdrawals: You can withdraw contributions and investment growth tax-free when purchasing a qualifying first home.
Under current federal rules, you receive $8,000 of contribution room in the year you open your first FHSA, with a $40,000 lifetime contribution limit. Unused participation room can be carried forward, subject to limits.
For example, a first-time buyer contributing $8,000 annually over five years could contribute $40,000 before investment growth.
Two eligible partners could potentially contribute a combined $80,000 over that period.
Something many buyers overlook: FHSA contribution room begins accumulating only after you open your first account. Opening one early can be beneficial, even if purchasing a home is still a few years away.
Learn more through the Canada Revenue Agency's FHSA guide.
5. Home Buyers' Plan: Can you use your RRSP for a down payment?
The federal Home Buyers' Plan (HBP) allows eligible buyers to withdraw up to $60,000 from their Registered Retirement Savings Plan (RRSP) to purchase or build a qualifying home.
Unlike a qualifying FHSA withdrawal, money withdrawn under the HBP must generally be repaid to your RRSP over 15 years, subject to applicable repayment-start rules.
Eligible buyers can also use the Home Buyers' Plan and FHSA for the same home purchase, provided they meet both programs' requirements.
For a couple where both buyers qualify, the combined HBP withdrawal limit could be $120,000.
This can help bridge the gap between existing savings and the down payment required for a property in Greater Victoria. However, buyers should consider how RRSP withdrawals may affect long-term retirement savings.
6. How much down payment do you need to buy your first home in Victoria?
The minimum down payment in Canada depends on the purchase price, not whether you're a first-time buyer.
As of 2026, the standard minimum requirements are:
Home purchase price
Minimum down payment
$500,000 or less
5%
Above $500,000 but below $1.5 million
5% of the first $500,000, plus 10% of the remainder
$1.5 million or more
20%
Minimum down payment examples for Victoria buyers
Purchase price
Minimum down payment
$450,000
$22,500
$550,000
$30,000
$650,000
$40,000
$750,000
$50,000
$850,000
$60,000
$1,000,000
$75,000
These are minimum requirements. Mortgage approval also depends on income, existing debt, credit history, qualifying interest rates and lender requirements.
Buyers putting down less than 20% typically require mortgage default insurance, which adds to the overall borrowing cost.
For a closer look at how your budget may influence location and property type, read our guide to comparing Victoria neighbourhoods at the $800,000 price point.
7. What closing costs should first-time home buyers expect in Victoria?
In addition to your down payment, first-time buyers should budget for legal fees, inspections, property transfer tax if applicable, and adjustments on closing.
Exact costs depend on the property, financing arrangements and applicable exemptions.
Closing expense
Typical planning estimate
Legal or notary fees and disbursements
$1,500–$2,500
Home inspection
$500–$900
Property appraisal, if required
$300–$600
Property transfer tax
Depends on purchase price and exemptions
Title insurance, if required
Varies by property and lender
Property tax and strata adjustments
Varies by closing date and property
Moving and initial setup
Depends on circumstances
These are illustrative budgeting ranges rather than quoted service prices. Obtain estimates from the professionals involved before subject removal and closing.
For buyers purchasing strata properties in Victoria, Saanich, Langford or Colwood, additional financial considerations include monthly strata fees, insurance deductibles, possible special levies and the building's financial position.
Understanding these expenses before writing an offer can help prevent unpleasant surprises later.
Our article on what a real estate lawyer does during the home-buying process explains how legal professionals handle transfers, adjustments and closing documentation.
8. First-time buyer example: How much cash do you need for a $600,000 condo in Victoria?
Let's compare two buyers purchasing a $600,000 condo: one purchasing a resale property and the other purchasing an eligible newly built home.
Both are assumed to qualify for the relevant first-time buyer programs and have the minimum down payment available.
Expense
Resale condo
Eligible new condo
Purchase price before GST
$600,000
$600,000
Minimum down payment
$35,000
$35,000
BC property transfer tax before exemption
$10,000
$10,000
Applicable BC PTT exemption
−$8,000
−$10,000
PTT payable
$2,000
$0
GST before rebate
$0
$30,000
Qualifying GST rebate
$0
−$30,000
Estimated other closing costs
$3,000
$3,000
Estimated cash required
$40,000
$38,000
This is an illustrative comparison. It assumes the builder credits the full GST rebate at closing, tax exemptions apply in full, and a $3,000 allowance for other closing costs. Mortgage insurance premiums, applicable taxes on insurance, adjustments and other property-specific expenses are not included. Final down-payment and mortgage calculations must be confirmed with the lender.
The takeaway isn't that new construction is always cheaper.
It's that purchase price and total purchase cost are not the same thing.
A resale property may offer different advantages, such as an established strata corporation, existing amenities or more flexibility around possession. New construction may offer tax savings, warranties and newer building systems.
The right decision depends on more than the listing price.
9. Where should first-time buyers consider purchasing in Greater Victoria?
Your ideal neighbourhood depends on your budget, commute, lifestyle and the kind of home you want to own.
Langford and the Westshore
Langford and neighbouring Westshore communities provide a mix of newer condominiums, townhomes and detached houses. Buyers comparing these areas should consider commuting, building age, strata costs and planned growth.
Read our guide to hidden-gem neighbourhoods in Langford, Colwood and View Royal.
Downtown Victoria and Esquimalt
Buyers who prioritize walkability, nearby employment, restaurants and transit may prefer a condominium closer to Victoria's urban core. Compare monthly ownership expenses and building condition alongside the location.
Saanich and View Royal
These communities offer established residential neighbourhoods, varied housing types and access to different parts of Greater Victoria. Property age, transit access and maintenance requirements can influence overall affordability.
You can explore available properties through our Greater Victoria home search.
10. What should you do before buying your first home?
Before beginning your property search, take the time to establish your financial position and understand the buying process.
Speak with a mortgage professional. Confirm your borrowing capacity, qualifying rate and comfortable monthly payment.
Review your eligibility for rebates and exemptions. Consider provincial property transfer tax programs, the federal GST rebate, FHSA and HBP.
Establish your complete budget. Include the down payment, closing costs, ongoing expenses and a reserve for unexpected repairs.
Compare neighbourhoods and property types. Consider both today's needs and how the home may suit you over the next several years.
Understand the conditions in your offer. Financing, inspection and strata document review can play an important role in protecting your interests.
For more on what happens after mortgage pre-approval, read The Real Timeline: How Long Does It Take to Buy a Home?.
Frequently Asked Questions About Buying Your First Home in Victoria
Can you buy a home in Victoria with a 5% down payment?
Yes. Eligible buyers purchasing a home for $500,000 or less may qualify with a 5% down payment. Above $500,000 and below $1.5 million, the minimum is 5% on the first $500,000 and 10% on the remainder. Mortgage qualification and insurance requirements still apply.
Do first-time home buyers pay property transfer tax in BC?
Sometimes. Eligible buyers purchasing a home for $500,000 or less may receive a full exemption. For homes above $500,000 and up to $835,000, the exemption is generally limited to $8,000. A partial exemption is available up to, but not including, $860,000.
Do first-time home buyers pay GST on resale homes in Victoria?
Generally, no. The sale of a previously occupied residential property is normally exempt from GST. Newly constructed homes are generally subject to GST, although eligible first-time purchasers may qualify for the federal rebate.
Can couples combine first-time home buyer programs?
Yes, in certain circumstances. Eligible partners may each use their own FHSA contribution room and Home Buyers' Plan withdrawal entitlement. However, provincial property transfer tax exemptions depend on each purchaser's eligibility and ownership interest. Tax credits and rebates also have their own rules.
Can you qualify as a first-time home buyer if you previously owned a home?
It depends on the program. Some federal programs use a four-calendar-year lookback test, while BC's first-time buyer property transfer tax exemption has different previous ownership requirements. A buyer who qualifies under one program may not qualify under another.
How much money should you save before buying a home in Victoria?
Your savings should cover the required down payment, closing costs and an emergency reserve. For example, a first-time buyer considering a $600,000 resale condo could need approximately $40,000 in upfront cash under the assumptions outlined earlier. Actual requirements depend on the purchase and financing details.
Buying Your First Home in Victoria Starts With a Clear Plan
For many first-time buyers, the biggest challenge isn't finding a property. It's understanding how the numbers fit together and knowing which decisions deserve the most attention.
A tax exemption might make one property more affordable than another. A new-home GST rebate could change your options. And the right mortgage structure can influence how comfortably you manage ownership costs after moving in.
At Faber Real Estate Group, we believe buying your first home should begin with education, not pressure.
Whether you're exploring your options or preparing to purchase in the coming months, our team can help you understand the local market, compare properties and build a buying strategy around your goals.
Connect with Faber Real Estate Group to discuss buying your first home in Greater Victoria.
Scott M.., 5-Star Review, via Google
“Scott & Cal and their team were excellent in helping me secure a new condo at the Pavilion- knowledgeable, personable, and great service. Would highly recommend their team if you’re looking for a dynamic realtor in the CRD!”
Faber Real Estate Group
Royal LePage Coast Capital Realty
📞 250-244-3430
📧 [email protected]
ℹ️ Scott Faber PREC
ℹ️ Cal Faber PREC
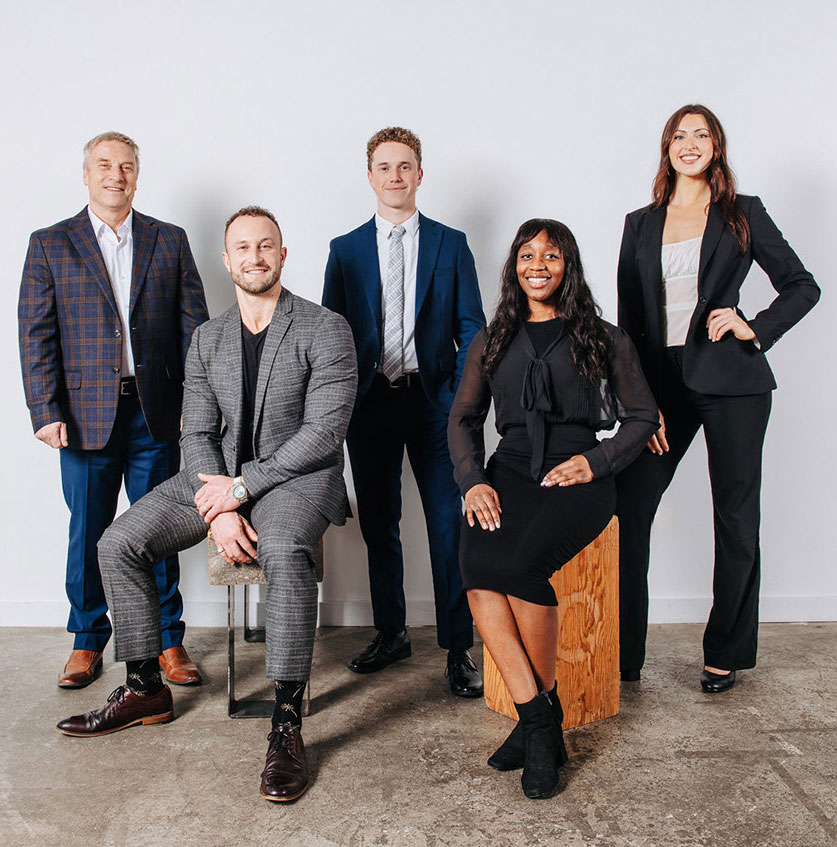
Vanessa Wood, Zachary Parsons, Sophie Taylor
Building Lasting Relationships, One Home at a Time.
Information current to October 8, 2026. Government programs, tax rules and eligibility requirements can change. This article provides general educational information, not personalized tax, legal or mortgage advice. Confirm your eligibility with the relevant government agency and qualified professionals before committing to a purchase.
Read more