Posts Tagged ‘buying a home in Victoria’
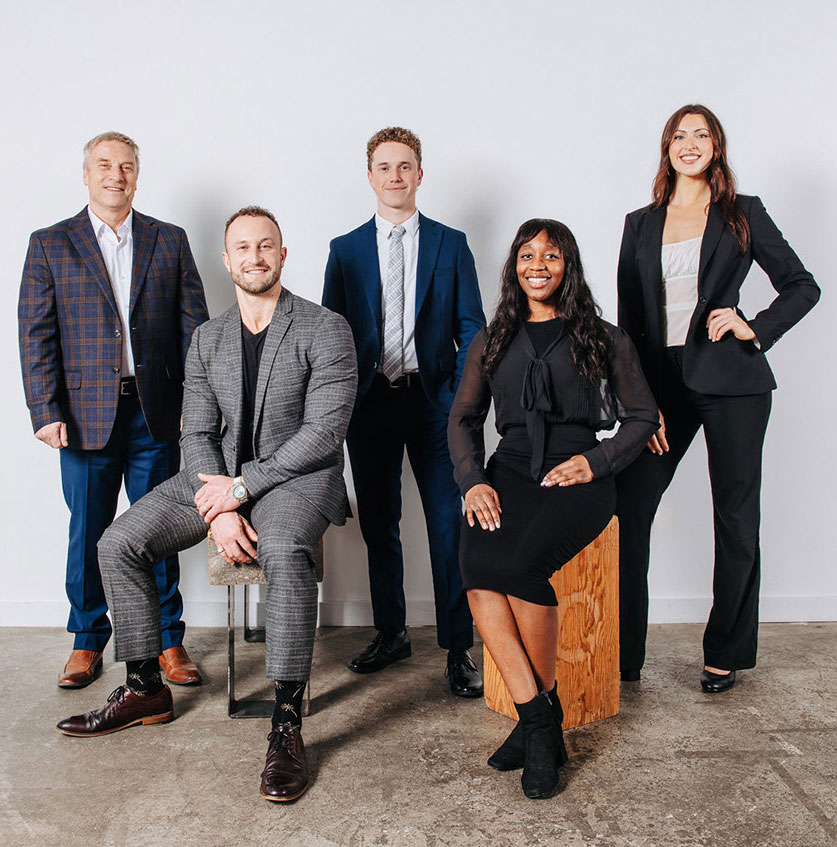
What Does the Bank of Canada’s October 2026 Rate Hike Mean for Victoria Buyers and Sellers? Canada's first interest rate increase in over three years brings new considerations for Greater Victoria homebuyers, sellers, and homeowners. After more than a year of unchanged interest rates, the Bank of Canada has made a move that could influence housing decisions across Greater Victoria. On October 28, 2026, the central bank increased its overnight lending rate by 25 basis points, bringing it to 2.50% from 2.25%. For buyers, the increase means potentially higher mortgage payments and slightly reduced borrowing power. For sellers, it introduces another consideration into a housing market where buyers already have more properties to choose from. But does a quarter-point interest rate increase significantly change Victoria's real estate market? Not necessarily. The real impact depends on mortgage financing, local housing inventory, and the circumstances of individual buyers and sellers. Why Did the Bank of Canada Raise Interest Rates? The October increase was the Bank of Canada's first rate hike since July 2023, reflecting growing concerns about inflation. Higher energy prices and increased business costs have contributed to inflation remaining above the Bank's 2% target. The central bank is concerned that these pressures could spread into other parts of the economy, making inflation more difficult to control. At the same time, Canada's economy has demonstrated greater resilience than previously expected, giving policymakers more room to increase borrowing costs. The Bank now projects inflation will average approximately 3% in 2027 before returning toward its 2% target in the middle of 2028. Although further increases remain possible, the Bank has emphasized that future decisions will depend on incoming economic information. For Canadian homeowners and prospective buyers, this means interest rates remain an important consideration when planning their next move. How Much More Could a Mortgage Cost After the Rate Hike? A 0.25 percentage-point increase might sound relatively small, but its impact becomes more noticeable when applied to larger mortgage balances. Consider a buyer purchasing a home in Greater Victoria with a $600,000 mortgage amortized over 25 years. If their mortgage interest rate increased from an illustrative 4.50% to 4.75%, the monthly payments on an adjustable-payment mortgage would change approximately as follows: Mortgage Scenario Monthly Payment $600,000 at 4.50% $3,335 $600,000 at 4.75% $3,421 Monthly Difference +$86 Annual Difference +$1,032 Illustrative calculation assuming monthly compounding and a 25-year amortization. Actual payments depend on mortgage terms, compounding, payment structure, and lender. That additional $86 per month may not completely change someone's purchasing plans, but it adds to other homeownership expenses such as property taxes, utilities, insurance, and maintenance. For buyers already approaching the upper end of their approved budget, the increase deserves careful consideration. Will Fixed and Variable Mortgage Rates Both Increase? Not necessarily. The type of mortgage matters. Variable-rate mortgages are more directly affected by changes to the Bank of Canada's overnight rate. Following the October announcement, National Bank increased its prime lending rate to 4.70%, effective October 29, 2026. Other lenders may have their own rates and terms. For homeowners with adjustable-payment variable-rate mortgages, higher interest rates generally result in larger payments. Homeowners with fixed-payment variable mortgages may see their monthly payments remain unchanged, but a larger portion of each payment could go toward interest rather than reducing their mortgage balance. Fixed-rate mortgages work differently. Existing fixed-rate mortgage holders generally maintain their contracted interest rate until their term expires. New fixed mortgage rates are influenced more directly by Government of Canada bond yields, lender funding costs, and competition, rather than moving automatically with every Bank of Canada announcement. This distinction is important for buyers deciding between mortgage options and homeowners approaching renewal. What Does the Rate Increase Mean for Victoria Homebuyers? For buyers considering purchasing in Victoria, Saanich, Langford, Colwood, or elsewhere in Greater Victoria, the rate increase introduces two considerations: monthly affordability and mortgage qualification. Higher borrowing costs can reduce the maximum mortgage amount some households qualify for. At federally regulated lenders, uninsured mortgage applicants generally need to qualify at the greater of their contract rate plus two percentage points or 5.25%. As mortgage rates change, buyers may need to revisit their pre-approval and confirm their purchasing budget. However, borrowing costs are only one part of the decision. Greater Victoria entered November with more housing inventory than a year earlier, providing buyers with additional opportunities to compare properties. For example, buyers considering a condominium in downtown Victoria may find themselves comparing several similar properties, while someone searching for a detached family home in a particular Saanich neighbourhood may have fewer alternatives. Rather than reacting to the rate announcement alone, buyers should consider their monthly budget, available listings, recent comparable sales, and long-term housing needs. A lower purchase price can sometimes offset higher borrowing costs, but only when the numbers work for the individual buyer. How Is Greater Victoria's Real Estate Market Performing? The October interest rate announcement arrived as Greater Victoria's housing market was showing signs of improved sales activity. According to the Victoria Real Estate Board's October 2026 statistics: 573 properties sold, up 23.8% from September but down 7.1% year over year. 3,594 active listings remained available at month-end, approximately 5% more than October 2025. $1,288,600 was the MLS® Home Price Index benchmark for a single-family home in the Victoria Core, up 0.7% year over year. $533,900 was the Victoria Core condominium benchmark, down 2.8% year over year. These figures point to a market with continued buyer activity, meaningful housing selection, and different pricing trends across property types. Importantly, because the Bank of Canada's announcement occurred on October 28, the October statistics should not be interpreted as showing the effects of the rate hike. Any change in buyer behaviour resulting from the announcement may take time to appear in sales activity and housing prices. What Does the Interest Rate Increase Mean for Victoria Home Sellers? For homeowners thinking about selling, higher mortgage rates can influence how buyers approach a purchase. When financing becomes more expensive, some buyers may reconsider their budget, adjust their preferred property type, or take longer to make a decision. That does not mean demand disappears. Greater Victoria recorded a substantial month-over-month increase in sales during October, demonstrating that buyers remain active even in a more cautious environment. The difference is that buyers have more alternatives. Sellers should pay particular attention to the number of comparable listings competing for the same buyers, how long those properties have been available, and what similar homes have recently sold for. For example, a condominium seller in Langford may face competition from newer developments and existing resale listings. Meanwhile, a detached homeowner in an established Victoria neighbourhood may be competing within a much smaller selection of comparable properties. These differences can influence pricing, marketing, and negotiation strategies more than a single national interest rate announcement. In a market offering buyers greater choice, pricing a property appropriately from the beginning becomes increasingly important. Should Buyers Wait for Interest Rates to Come Down? Trying to predict the direction of interest rates can make an already complicated homebuying decision more difficult. The Bank of Canada's October announcement demonstrates how quickly expectations can change. Earlier in 2026, discussions focused largely on when interest rates might decrease. Persistent inflation has now shifted that conversation toward the possibility of additional increases. For prospective buyers, waiting may be reasonable if their finances, employment circumstances, or down payment are not yet where they need to be. However, waiting solely for lower rates introduces uncertainty. Mortgage rates could change, housing prices could move, and the number of available properties may look different several months from now. The better question is whether purchasing a particular property makes financial and personal sense under current conditions. A comfortable monthly payment, appropriate emergency savings, and a home that meets long-term needs are more reliable starting points than attempting to predict the next rate announcement. What Should Homeowners With Upcoming Mortgage Renewals Do? For existing homeowners, the October announcement is another reason to review mortgage renewal dates and current financing arrangements. Those approaching renewal should understand how their potential new interest rate compares with their existing contract. Even homeowners with fixed-rate mortgages may experience a payment adjustment when their term expires. It may be helpful to speak with a mortgage professional before the renewal date to compare available products, assess payment scenarios, and determine whether changes to the mortgage structure make sense. For homeowners considering selling, downsizing, or purchasing another property, understanding the mortgage balance, renewal conditions, and any potential prepayment penalties can help establish a realistic plan. Will the October Rate Hike Cause Victoria Home Prices to Fall? There is no reliable way to conclude that a single 0.25 percentage-point increase will cause Greater Victoria home prices to decline. Higher borrowing costs can reduce purchasing power and influence housing demand. However, property values also depend on available inventory, employment conditions, household finances, and demand within individual neighbourhoods. October's market statistics already show why this distinction matters. Detached home benchmark prices in the Victoria Core were slightly higher than a year ago, while condominium benchmarks were lower. That difference existed before the October rate announcement could materially influence completed sales. Moving forward, changes in mortgage rates may add pressure to certain market segments, particularly where affordability is already stretched or inventory is plentiful. Other properties may continue to attract interest because of their location, condition, limited supply, or suitability for buyers' needs. What Happens Next for Greater Victoria Real Estate? The Bank of Canada's next scheduled interest rate announcement is December 9, 2026. Until then, buyers, sellers, and homeowners will be watching inflation, economic conditions, and the response of mortgage lenders. For Greater Victoria, the more useful indicators will include whether sales activity continues to recover, how inventory changes heading into winter, and whether prices respond differently across neighbourhoods and property types. The October rate increase is worth paying attention to, but it is only one part of the housing market. The strongest real estate decisions come from understanding how borrowing costs, property values, and personal circumstances fit together. Thinking About Buying or Selling in Greater Victoria? Whether you're preparing to purchase your first home, considering a move, or wondering how current market conditions affect your property's value, understanding the numbers is a good place to start. At Faber Real Estate Group, we help buyers and sellers evaluate local market conditions and make informed decisions based on their individual goals. Interest rates may influence affordability, but the right real estate strategy depends on more than the latest announcement. Curious how October's rate increase and current housing market conditions relate to your neighbourhood or the value of your home? We'd be happy to take a closer look. Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.” Connect with Faber Real Estate Group Sources and further reading Bank of Canada — October 28, 2026 Rate Announcement Victoria Real Estate Board — October 2026 Market Statistics Financial Consumer Agency of Canada — Interest on Mortgages OSFI — Minimum Qualifying Rate for Uninsured Mortgages Published November 2026. Mortgage examples are illustrative and do not constitute lending or financial advice.
Read more
Greater Victoria Real Estate Market Update: October 2026 Sales activity rebounds as Greater Victoria returns to a more balanced housing market. Greater Victoria's real estate market picked up in October 2026, with more homes selling compared to September, inventory remaining above last year's levels, and prices moving differently across property types. According to the Victoria Real Estate Board (VREB), 573 properties sold across the region, a 23.8% increase from September but 7.1% fewer than October 2025. After September's slower activity pushed the region into buyer's market territory, October marked a return to more balanced conditions. For buyers, that means continued selection and opportunities to compare properties. For sellers, it reinforces the importance of competitive pricing and presentation. October 2026 Market Statistics at a Glance Market Indicator October 2026 Year-over-Year Change Total Property Sales 573 -7.1% Single-Family Home Sales 303 -13.4% Condominium Sales 135 -15.1% Active Listings 3,594 +5.0% Victoria Core Detached Benchmark $1,288,600 +0.7% Victoria Core Condo Benchmark $533,900 -2.8% Source: Victoria Real Estate Board, October 2026. Sales and inventory reflect the VREB region. Benchmark prices are for the Victoria Core. Sales Activity Rebounds From September October brought a noticeable improvement in market activity. The 573 sales represented 110 more transactions than September's 463, bringing activity close to the previous five-year October average of 581 sales. However, sales remained below October 2025 levels, particularly for detached homes and condominiums. This suggests that while buyers became more active in October, the market has not returned to the more competitive conditions experienced in previous years. Instead, transactions are taking place in an environment where buyers have more alternatives and can evaluate purchases with greater care. Housing Inventory Remains Higher Than Last Year Greater Victoria finished October with 3,594 active MLS® listings, approximately 5% more than the same time last year. Although inventory declined by 5.7% compared to September, buyers still have more properties to consider than they did a year ago. Another 1,138 new listings entered the market throughout October, slightly exceeding the five-year October average of 1,060. For buyers, this additional inventory can mean more flexibility when comparing homes, negotiating terms, and completing due diligence. For sellers, it means understanding the competition matters. A home is not simply competing against recent sales. It is also competing against every comparable property currently available. Victoria Home Prices: Detached Homes Hold Steady While Condos Soften October's benchmark prices tell two different stories. The MLS® Home Price Index benchmark for a single-family home in the Victoria Core reached $1,288,600, an increase of 0.7% compared to October 2025. Condominiums experienced a different result. The Victoria Core benchmark condominium price declined 2.8% year over year to $533,900. Compared to September, the detached benchmark increased by $8,500, while the condominium benchmark declined by $13,900. These differences highlight why it is difficult to describe Greater Victoria's housing market with a single price trend. Detached homes in established neighbourhoods may face different levels of competition than condominiums in areas with significant new construction or a larger selection of comparable listings. Benchmark prices also represent typical properties within a particular market segment. They are not the same as average or median selling prices, nor do they establish the value of an individual home. What Does October's Market Mean for Buyers? For buyers considering a home in Victoria, Saanich, Langford, Colwood, or elsewhere in Greater Victoria, October's market continues to offer opportunities for thoughtful decision-making. Higher inventory means buyers may have more options across different neighbourhoods and property types. However, greater choice does not necessarily mean every seller is prepared to negotiate significantly. Well-priced homes in desirable locations can still attract strong interest. The most effective approach is to understand recent comparable sales, assess the property's condition, confirm financing, and consider the long-term suitability of the purchase. Rather than focusing exclusively on whether prices might rise or fall next month, buyers should consider whether a particular property makes sense for their financial circumstances and future plans. What Does October's Market Mean for Sellers? For homeowners thinking about selling, October demonstrated that buyers are still active. The increase in transactions from September is encouraging, but the higher inventory levels mean sellers need to approach the market with realistic expectations. Pricing a home based solely on what a neighbour sold for earlier in the year may not reflect current competition. Buyers are comparing homes carefully, particularly when several similar listings are available. A successful selling strategy starts with understanding recent sales, current inventory, property condition, and the features that distinguish a home within its neighbourhood. Pricing and presentation should work together to give buyers a clear reason to consider the property. Is Greater Victoria in a Buyer's or Seller's Market? October's results point to a more balanced Greater Victoria real estate market, following September's brief shift into buyer's market territory. A balanced market generally means neither buyers nor sellers have a clear advantage across the entire region. However, conditions can vary significantly. A detached home in Oak Bay, a condominium in downtown Victoria, and a newer townhome in Langford may each face different levels of demand, inventory, and competition. That is why neighbourhood-specific information matters more than broad market headlines when making real estate decisions. Looking Ahead: What Can We Expect From Victoria's Housing Market? As Greater Victoria moves into the final months of 2026, October's results offer some perspective. Sales activity improved, inventory remains healthy, and prices continue to respond differently depending on the type of property. The coming months will help establish whether October's rebound reflects a more sustained improvement in demand or simply a stronger month following September's slowdown. For now, the market continues to provide opportunities for both buyers and sellers who understand their local conditions and approach decisions with realistic expectations. Thinking About Buying or Selling in Greater Victoria? Every neighbourhood has its own market conditions, and the regional statistics only tell part of the story. Whether you're considering selling your current home, purchasing your first property, or exploring opportunities in a different neighbourhood, our team at Faber Real Estate Group is here to help you understand the numbers and what they mean for your next move. Curious how October's market conditions relate to your neighbourhood or the value of your home? We'd be happy to take a closer look. Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.” Connect with Faber Real Estate Group Source: Victoria Real Estate Board — October 2026 MLS® Statistics. Market information reflects data released November 2, 2026.
Read more
How Much House Can I Afford in Victoria BC? Income & Mortgage Examples (2026) How much house can you afford in Victoria, BC, on your current income? It's one of the first questions buyers should answer before searching for properties. The challenge is that mortgage approval and comfortable homeownership aren't necessarily the same thing. You might qualify for an $800,000 property, but that doesn't automatically mean the monthly expenses will fit your lifestyle. Between mortgage payments, property taxes, strata fees, insurance and everyday living costs, your actual budget deserves more attention than your maximum borrowing limit. The short answer: A household earning approximately $100,000 to $110,000 per year might qualify for a $500,000 condo, while a household earning $180,000 to $195,000 could potentially qualify for a $1 million home, assuming a 20% down payment, limited existing debt and the mortgage conditions outlined below. These are illustrative estimates, not guaranteed mortgage approvals. Here's how income, down payments and mortgage qualification affect what you can afford in Greater Victoria in 2026. How Much House Can You Afford Based on Your Income in Victoria? Your household income plays a significant role in determining how much you can borrow, but lenders also consider your down payment, debt obligations, credit history and the ongoing expenses associated with the property. The following table provides a starting point for buyers exploring Greater Victoria. Victoria BC Home Affordability by Household Income Gross household income Illustrative home price $90,000 Around $400,000–$450,000 $110,000 Around $500,000–$550,000 $130,000 Around $600,000–$650,000 $150,000 Around $750,000–$800,000 $180,000 Around $900,000–$1,000,000 $220,000 Around $1,100,000–$1,250,000 These are broad planning estimates assuming approximately 20% down, a 25-year amortization, an illustrative 4.5% mortgage rate, qualification at 6.5%, reasonable property expenses and minimal additional debt. Individual borrowing capacity may differ substantially. Higher strata fees, property taxes or debt payments can reduce affordability. These figures illustrate why two buyers with similar incomes may have very different purchasing power. Someone earning $130,000 annually with no debts and a substantial down payment may qualify for considerably more than someone with the same income but significant vehicle and loan payments. Before looking at individual properties, it helps to understand how lenders calculate affordability. 1. How Do Mortgage Lenders Calculate What You Can Afford in BC? Canadian mortgage lenders generally use two debt-service ratios to assess whether you can afford a mortgage. These calculations compare your monthly expenses with your gross household income, meaning income before taxes. Gross Debt Service Ratio (GDS) The Gross Debt Service ratio measures how much of your income goes toward housing-related expenses. These generally include: Mortgage principal and interest. Property taxes. Heating expenses. 50% of condominium or strata fees, when applicable. For insured mortgage qualification, the standard GDS limit is generally 39% of gross household income. For example, a household earning $120,000 annually has gross monthly income of $10,000. At a 39% GDS ratio, approximately $3,900 per month may be available for qualifying housing expenses. Importantly, this is a lender qualification calculation, not necessarily a comfortable personal spending target. Total Debt Service Ratio (TDS) The Total Debt Service ratio includes housing expenses plus other debt obligations. These can include: Vehicle loans and leases. Credit card payments. Student loans. Personal loans. Lines of credit. For insured mortgage qualification, the standard TDS limit is generally 44%. That means a household earning $120,000 annually would typically have a maximum qualifying monthly debt allowance of approximately $4,400 under the 44% calculation. If that household already has $800 per month in other debt payments, less room remains for mortgage-related expenses. Lender requirements may differ for uninsured mortgages and certain borrowing situations. You can explore your own figures using the CMHC Debt Service Calculator. 2. What Is the Mortgage Stress Test in Canada in 2026? Canada's mortgage stress test requires borrowers at federally regulated lenders to demonstrate that they can afford mortgage payments at a higher interest rate than the rate they may actually receive. The qualifying interest rate is generally the higher of: Your mortgage contract rate plus 2 percentage points. 5.25%. For example, if you obtain a mortgage rate of 4.5%, the lender generally qualifies you at 6.5%. That doesn't mean you're actually paying 6.5% interest. It means the lender uses the higher rate when assessing your borrowing capacity. The stress test helps determine whether your finances could support higher payments. It also explains why a mortgage payment that appears affordable on paper may not translate into approval for the full purchase price. Use the Government of Canada's Mortgage Qualifier Tool to estimate how mortgage qualification works. 3. How Much Are Mortgage Payments in Victoria, BC? Let's compare monthly mortgage payments at several common Greater Victoria purchase prices. For consistency, these examples assume: A 20% down payment. A 25-year amortization. A hypothetical 4.5% fixed mortgage rate. Monthly principal and interest payments. No mortgage default insurance premium. Monthly Mortgage Payments by Home Price Purchase price Down payment (20%) Mortgage amount Approx. monthly payment $450,000 $90,000 $360,000 $1,993 $550,000 $110,000 $440,000 $2,435 $650,000 $130,000 $520,000 $2,878 $800,000 $160,000 $640,000 $3,542 $1,000,000 $200,000 $800,000 $4,428 $1,200,000 $240,000 $960,000 $5,314 Payments are rounded estimates using a 4.5% annual mortgage rate with Canadian semi-annual compounding. These are payment examples, not lender quotes or stress-test qualification payments. Property taxes, insurance, strata fees, utilities and maintenance are additional expenses. The difference between purchasing a $550,000 condo and an $800,000 townhome is approximately $1,107 per month in mortgage payments under these assumptions. However, that doesn't tell the entire story. A condo with higher strata fees may have ownership costs closer to those of a more expensive property with lower monthly operating expenses. A home's affordability depends on the total monthly cost of ownership, not just the mortgage payment. 4. How Much Income Do You Need to Buy a $550,000 Condo in Victoria? For a $550,000 condo with 20% down, the mortgage amount would be approximately $440,000. At an illustrative 4.5% mortgage rate, your monthly mortgage payment would be approximately $2,435. However, your lender would generally assess affordability using the higher 6.5% qualifying rate. When estimated property taxes, heating and 50% of strata fees are included, a household may need approximately $105,000 to $115,000 in annual gross income to qualify, assuming minimal additional debt. A $550,000 purchase is relevant because it is close to the Victoria Core condominium benchmark. According to the Victoria Real Estate Board, the benchmark price for a condominium in the Victoria Core was $547,800 in September 2026. That provides a useful reference point for buyers comparing condos in Victoria, Esquimalt, Saanich and the Westshore. 5. How Much Income Do You Need to Buy an $800,000 Home in Victoria? An $800,000 purchase with 20% down requires a $160,000 down payment. That leaves a $640,000 mortgage. At our illustrative 4.5% mortgage rate, the monthly payment would be approximately $3,542 before property expenses. Using the stress-test rate and reasonable allowances for property taxes, heating and potential strata fees, a household may need approximately $145,000 to $155,000 in gross annual income. At this price point, Greater Victoria buyers may be considering a variety of options, including: Townhomes in Langford or Colwood. Condominiums in established Victoria neighbourhoods. Townhomes in Saanich or View Royal. Smaller or older detached homes in certain outlying communities. The type of property available will depend on current inventory, condition and location. For a neighbourhood-by-neighbourhood comparison, read our article on What $800K Buys You in Victoria. 6. How Much Income Do You Need to Buy a $1 Million House in Victoria? With a 20% down payment, a $1 million purchase requires $200,000 upfront and leaves an $800,000 mortgage. At an illustrative 4.5% interest rate and 25-year amortization, the principal and interest payment would be approximately $4,428 per month. Under the 6.5% qualifying rate, the assessed payment would be higher. After allowing for property taxes and heating, a household may require approximately $180,000 to $195,000 in gross annual income, assuming minimal other debt and no major additional qualification expenses. Buyers should also consider that a detached home typically requires a separate maintenance budget for roofing, heating systems, landscaping and other repairs. For households purchasing a property with a secondary suite, some lenders may consider qualifying rental income. The amount and method used depend on the lender, loan structure and the property's eligibility. Rental income should never be assumed to guarantee a larger mortgage approval. 7. How Much Down Payment Do You Need to Buy a Home in Victoria? Your down payment directly affects your mortgage amount and the income needed to qualify. In Canada, the minimum down payment generally depends on the purchase price. Purchase price Minimum down payment $500,000 or less 5% More than $500,000 but below $1.5 million 5% of the first $500,000 plus 10% of the remainder $1.5 million or more 20% For example, a $600,000 home requires a minimum down payment of $35,000 under the standard rules. An $800,000 purchase requires at least $55,000. However, buyers putting down less than 20% generally require mortgage default insurance, subject to insurer eligibility. That insurance can increase the total amount borrowed. A larger down payment reduces the mortgage balance and may allow a buyer to qualify with less income. Review the Government of Canada's down payment requirements for further details. 8. How Does Your Down Payment Change What You Can Afford? Consider two buyers purchasing the same $800,000 property. Buyer A has a $160,000 down payment. Buyer B has a $300,000 down payment. Buyer A Buyer B Purchase price $800,000 $800,000 Down payment $160,000 $300,000 Mortgage $640,000 $500,000 Monthly payment at 4.5% $3,542 $2,767 Buyer B has a monthly mortgage payment approximately $775 lower because they are borrowing $140,000 less. That also reduces the mortgage payment used in the lender's affordability calculation. This is particularly relevant for buyers who are selling an existing home and using accumulated equity toward their next purchase. It can also help first-time buyers understand why additional down payment savings may have a meaningful effect on affordability. 9. What Other Costs Should You Include When Calculating Home Affordability? A mortgage pre-approval helps establish a potential purchase price, but homeownership involves ongoing expenses that deserve equal attention. Property Taxes Annual property taxes differ by municipality, property assessment and eligibility for applicable grants. A property in Victoria may have a different annual tax bill from a similarly priced home in Langford, Oak Bay or Saanich. You can learn more in our Municipal Property Tax Comparisons in Greater Victoria. Strata Fees Condo and townhome owners may pay monthly strata fees covering shared maintenance, building insurance, utilities and contributions to the contingency reserve fund. These fees vary by building, amenities and financial requirements. Although lenders may include only 50% of strata fees in their qualification calculation, owners remain responsible for paying the full amount. Insurance and Maintenance Insurance premiums depend on property type, location and coverage. Detached homeowners should also budget for ongoing repairs and replacement of major components. Older homes may require more immediate maintenance than newer properties, although new construction isn't entirely free from unexpected costs. Closing Costs Buyers also need sufficient funds for property transfer tax, legal fees, inspections and adjustments. Some buyers qualify for property transfer tax exemptions or GST rebates on eligible new construction. Review our Greater Victoria real estate resources to learn more about the home-buying process and related expenses. 10. Is It Cheaper to Buy in Langford Than Victoria? In many cases, Langford and the surrounding Westshore offer different housing options at lower purchase prices than comparable properties in the Victoria Core. However, the difference depends on property type, age, size and neighbourhood. A condominium in downtown Langford may provide more interior space than a similarly priced property in central Victoria. A townhome in Colwood may also offer a different combination of living space, parking and outdoor areas than a central Victoria condo. That said, price isn't the only consideration. Buyers should also account for commuting costs, property taxes, strata fees and proximity to employment. For someone working in downtown Victoria five days a week, transportation costs may change the financial comparison. For someone working remotely or employed in Langford, purchasing in the Westshore may offer both convenience and additional housing options. Read our guide to Hidden Gem Neighbourhoods in Langford, Colwood and View Royal. 11. Is 2026 a Good Time to Buy in Victoria? Greater Victoria's housing market has experienced changing conditions throughout 2026. According to the Victoria Real Estate Board's September 2026 statistics: 463 properties sold during September. Sales decreased 16.4% compared with September 2025. Active inventory reached 3,811 listings. The Victoria Core detached home benchmark was $1,280,100. The Victoria Core condo benchmark was $547,800. The Board described September's market conditions as entering buyer's market territory, while cautioning that one month does not necessarily indicate a long-term trend. For qualified buyers, additional inventory can mean more properties to compare and potentially greater negotiating flexibility. However, mortgage affordability remains a separate issue. A buyer may have more choices in the market but still face borrowing limitations due to income, interest rates or debt obligations. The better question isn't simply whether it's a good time to buy. It's whether the property, monthly expenses and purchase terms make sense for your financial situation. 12. Should You Buy at Your Maximum Mortgage Approval? Just because a lender approves you for a certain purchase price doesn't mean you should spend that amount. Mortgage qualification is based on financial criteria, but it doesn't fully account for every lifestyle choice or future financial goal. Before purchasing at your maximum budget, consider: How much you want to save each month. Whether you expect major life changes. Your current and future transportation costs. Whether you plan to have children or change employment. The maintenance requirements of the property. Your comfort level if mortgage rates increase at renewal. For example, a household approved for an $850,000 property may prefer buying at $700,000. That difference could provide more financial flexibility for travel, savings, retirement contributions or unexpected expenses. A comfortable ownership experience often begins with choosing a purchase price below your absolute borrowing limit. Frequently Asked Questions About Home Affordability in Victoria, BC Can I afford a house in Victoria on a $100,000 salary? A household earning $100,000 annually may qualify for a home around $450,000 to $500,000 under certain assumptions, including a 20% down payment, limited debt and manageable property expenses. Actual approval depends on the lender and individual finances. How much mortgage can I qualify for with a $150,000 income in BC? With strong credit, minimal existing debt and a suitable down payment, a $150,000 household income might support a purchase around $750,000 to $800,000. Mortgage qualification also depends on the stress test, property taxes, heating and strata fees. How much income do you need for a $1 million home in Victoria? With 20% down and limited existing debt, a household may need approximately $180,000 to $195,000 annually under the assumptions used in this article. A larger down payment may reduce the income required. Do car payments affect mortgage qualification in BC? Yes. Car loans and leases count toward your total debt-service calculation. A significant monthly vehicle payment can reduce how much mortgage debt a lender will approve. Can I buy a house in Victoria with less than 20% down? Yes, eligible buyers can purchase qualifying properties with less than 20% down. Mortgage default insurance is generally required, and the minimum down payment depends on the purchase price. Does buying with a partner increase mortgage affordability? Potentially. A joint application may combine eligible household income, allowing buyers to qualify for a larger mortgage. However, lenders also consider both applicants' debts, credit histories and financial obligations. Is it better to get pre-approved before looking at homes in Victoria? Yes. Mortgage pre-approval helps establish a realistic price range and provides an opportunity to identify potential financing issues before making an offer. However, pre-approval is not a guarantee of final mortgage funding. How Much House Should You Actually Buy in Victoria? Knowing how much a lender may approve is useful, but understanding how much you can comfortably afford is what matters most. Your income establishes part of the equation. Your down payment, existing debts, monthly expenses and long-term priorities determine the rest. For some buyers, that means choosing a condo near downtown Victoria. Others may find better value in a Langford townhome or an established property in Saanich. There isn't one property type or price point that works for everyone. The goal is to purchase a home that fits your needs without putting unnecessary pressure on your finances. At Faber Real Estate Group, we help buyers understand Greater Victoria's neighbourhoods, compare property options and make informed decisions based on their individual circumstances. Whether you're buying your first home, relocating to Victoria or planning your next move, our team can help you connect your budget with realistic opportunities in the local market. Contact Faber Real Estate Group to discuss what you can afford in Greater Victoria. Jordan Z., 5-Star Review, via Google “Working with Zach Parsons and the Faber Real Estate Group made buying our first home a great experience from start to finish. As first-time buyers, we had a lot to learn, but Zach was there every step of the way. He was always quick to answer questions, explain the process, and offer honest guidance without ever making us feel rushed or pressured into a decision. I highly recommend Zach Parsons and the Faber Real Estate Group to anyone looking to buy or sell a home. If you're looking for a realtor who truly puts his clients first, you won't be disappointed. Thanks again for helping us find our first home!” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber PREC ℹ️ Cal Faber PREC Vanessa Wood, Zachary Parsons, Sophie Taylor Building Lasting Relationships, One Home at a Time. Information updated October 8, 2026. Mortgage payments and income ranges are illustrative estimates, not financing offers or pre-approvals. Actual eligibility depends on lender policies, credit, debt, down payment and property-related expenses. Consult a qualified mortgage professional for personalized financing advice.
Read more
The Victoria fall real estate market 2026 is shaping up to be active but balanced. August sales were stronger than a year ago, inventory remains healthy, and buyers continue to have enough choice to be selective. That combination matters. We are seeing more activity, but not the conditions that would suggest a return to the highly competitive market of a few years ago. If current trends continue, this fall could create opportunities on both sides: buyers should continue to have selection, while properly priced and well-presented homes can still attract strong interest. What Are Current Victoria Real Estate Trends Telling Us? According to the Victoria Real Estate Board’s August 2026 market report, 591 properties sold across Greater Victoria in August, 12.6% more than August 2025. Single-family home sales increased 15.3% year over year, while condominium sales increased 15.1%. At the same time, there were 3,662 active listings at the end of August. That was 1.7% more than a year earlier, even after inventory declined 4.8% from July. VREB described current conditions as a stable, balanced market. The important part is the combination: Sales are stronger than last year Inventory remains relatively healthy Buyers still have choices Good properties are selling Overpriced listings can still sit That gives us a useful starting point for what the fall market may look like. Will the Victoria Fall Real Estate Market 2026 Be Busier? We expect September and October to remain active, particularly if the momentum from August carries forward. Fall often brings buyers and sellers back into the market after summer travel and vacations. This year, that seasonal shift is starting from a stronger sales base than we saw at the same time last year. However, stronger activity does not automatically mean a seller's market. With more than 3,600 active listings at the end of August, buyers still have alternatives. That means the better description may be: More activity, without widespread urgency. Earlier this summer, we looked at this decision from the buyer's perspective in Should Victoria Buyers Buy Now or Wait Until Fall?. The same principle still applies: waiting only makes sense if something about your personal situation or the available market is likely to improve. Buyers Should Still Have Good Selection Inventory has been one of the defining features of the 2026 Victoria market. Buyers have considerably more opportunity to compare properties than they did during the extremely tight markets of previous years. That means buyers can spend more time comparing: Location Price Property condition Floor plan Strata fees Parking and storage Renovation requirements Days on market Recent comparable sales More inventory does not mean every property is negotiable. However, it does mean buyers often have an alternative if one seller's price or terms do not make sense. For buyers trying to establish a realistic budget before shopping this fall, our guide on how much income you need to buy a home in Victoria breaks down several common Greater Victoria price points and mortgage qualification scenarios. Well-Priced Homes Could Still Sell Quickly One of the biggest misconceptions about a balanced market is that everything sells slowly. That is not what we are seeing. A well-priced home in a desirable location can still generate strong activity, particularly when it compares favourably with competing listings. Consider two similar properties. One launches at a price supported by recent comparable sales, is professionally presented, and is easy for buyers to view. The other enters the market above recent sales because the seller wants to "leave room to negotiate." Buyers now have enough inventory to recognize the difference. Instead of negotiating with the overpriced seller, they may simply buy the better-valued property. This is why the Victoria fall real estate market 2026 could feel competitive for some sellers and slow for others at exactly the same time. Do We Expect Victoria Home Prices to Rise This Fall? A major short-term price increase is not the trend we would plan around. Current conditions point more toward relative price stability than either a rapid increase or significant correction. Healthy inventory limits some of the pressure that normally drives prices quickly higher. At the same time, stronger year-over-year sales suggest there is still meaningful demand in the market. That creates a middle ground. Rather than focusing on whether "Victoria prices" are moving up or down, buyers and sellers should pay closer attention to their specific segment. A detached home in Oak Bay can behave differently from: A downtown Victoria condo A Langford townhouse A new-build condo A family home in Colwood An older Saanich property requiring renovations Greater Victoria is not one market. It is a collection of smaller markets that can behave differently at the same time. Could Condos See More Activity This Fall? Condos are one segment worth watching closely. VREB reported 175 condominium sales in August, up 15.1% from August 2025. That does not guarantee the condo market will strengthen throughout the fall, but the year-over-year improvement is encouraging. Condo buyers are still able to compare similar listings based on factors such as: Strata fees Building condition Depreciation reports Parking Storage Orientation Floor plan Building age Upcoming assessments Location As a result, individual units can perform very differently even within the same building. A good floor plan, desirable exposure, parking, storage, reasonable strata fees, and competitive pricing can matter more than broad condo-market headlines. What Do Interest Rates Mean for the Fall Market? Interest rates remain another important piece of the fall outlook. On September 2, the Bank of Canada held its policy interest rate at 2.25%. The rate has remained at that level since late 2025. For buyers, that provides more stability than a market where borrowing costs are changing rapidly. However, economic uncertainty has not disappeared. The Bank of Canada continues to monitor inflation, economic growth, tariffs, energy prices, and broader global conditions. That means buyers should be careful about building their purchase strategy around predictions of significantly lower mortgage rates. A better approach is to buy based on a monthly payment you can comfortably manage today. What Does BCREA Expect From the B.C. Housing Market? The broader provincial outlook also supports the idea of a gradual market recovery rather than a dramatic surge. In its 2026 Third Quarter Housing Forecast, the British Columbia Real Estate Association forecast B.C. MLS® residential sales to decline 1.2% overall in 2026 before increasing 7.5% in 2027. That forecast reinforces an important point. The market does not need to boom for conditions to improve. A period of stable prices, healthy inventory and gradually improving sales activity can create a healthier environment for both buyers and sellers. Expect More Negotiation on Listings That Have Been Sitting Fall could provide good negotiating opportunities, but buyers need to know where to look. A new listing that is priced correctly may leave very little room for negotiation. A property that has been on the market for 40, 60 or 90 days may be a different conversation. Buyers should look for: Longer days on market Previous price reductions Vacant properties Sellers with specific timing needs Listings competing against several similar homes Properties requiring renovations or updates Price is also not the only part of an offer worth negotiating. Our guide to what buyers should negotiate beyond the purchase price looks at deposits, subjects, possession dates, included items, due diligence periods and other terms that can materially affect a purchase. What Could Change the Victoria Fall Real Estate Market 2026? There are three major trends we will be watching throughout the fall. 1. Inventory If sales remain strong while fewer new listings reach the market, conditions could gradually become more competitive. Inventory also typically declines as we move toward winter, so the relationship between new listings and sales will matter more than either number on its own. 2. Interest Rates Mortgage affordability will continue to influence buyer purchasing power. Even modest changes in mortgage rates can affect monthly payments and the price range buyers are comfortable considering. 3. Buyer Confidence Real estate decisions are not based on numbers alone. Employment, economic uncertainty, trade conditions, inflation and consumer confidence can all affect whether buyers decide to move forward or wait. These forces are one reason we prefer using current market evidence rather than making aggressive predictions about where prices will be several months from now. What Should Buyers Expect This Fall? For buyers, this fall could offer a useful balance between selection and activity. There should still be opportunities to compare listings, conduct proper due diligence and negotiate when a property has been sitting. However, buyers should not assume every listing will eventually reduce its price. When a well-priced home appears in a desirable location, being prepared matters. Before actively shopping, buyers should ideally have: Financing organized A comfortable monthly budget established Target neighbourhoods identified Clear priorities An understanding of recent comparable sales A strategy for writing an offer if the right property appears You can also explore our current Greater Victoria developments if new construction or pre-sale opportunities are part of your search. What Should Sellers Expect This Fall? Sellers may benefit from increased fall activity, but buyers are unlikely to overlook poor positioning simply because more people are searching. Before listing, sellers should understand: What is currently for sale nearby What recently sold Which competing listings reduced their prices How their home compares in condition Which price range reaches the largest buyer pool Whether similar homes are selling or sitting The first few weeks of a listing remain extremely important. A seller who starts too high may spend the strongest period of buyer attention chasing the market downward later. Our Victoria Fall Real Estate Market 2026 Outlook Based on the trends available today, we expect the fall market to be characterized by: Steady sales activity Healthy buyer selection Relatively stable prices Continued buyer selectiveness Strong activity around well-priced homes More negotiating power on stale or overpriced listings Gradually declining inventory as winter approaches Significant differences between neighbourhoods and property types The strongest signal from the current market is not that buyers or sellers clearly have the upper hand. Instead, the advantage increasingly belongs to whoever understands the specific property and micro-market better. Planning a Move in Greater Victoria This Fall? Market statistics are a useful starting point, but they do not tell you whether a specific home in Langford, Saanich, Oak Bay, Victoria, Colwood or View Royal is priced correctly. If you are considering buying or selling this fall, our team can break the market down by neighbourhood, property type, price range, recent comparable sales and current competition. You can also learn more about our approach on our Buy With Us page or Sell With Us page. The fall market may create opportunities, but the best strategy is not trying to predict every move the market will make. It is understanding today's conditions well enough to recognize a good decision when it appears. Cammie J., 5-Star Review, via Google “I can’t say enough good things about working with Scott and Sophie at Faber Real Estate Group. Their communication was fantastic from start to finish, and they patiently worked with us for six months while we looked for a very specific type of house in a specific area of town. We found our perfect house because Scott knew it was coming on the market, which speaks to their experience and local knowledge. They were professional, responsive, informed, and always followed through. They also continued to support us after the sale, helping with contacts, moving-day details, paperwork, and making sure everything went smoothly. They made the whole experience feel positive and well supported. I cannot recommend Scott and Sophie enough.!” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.”
Read more
If you are wondering how much income you need to buy a home in Victoria, BC, the short answer is that a household income of roughly $105,000 could support a $550,000 condo, while a $1 million home may require closer to $180,000 in household income under the assumptions used below. However, income is only one part of mortgage qualification. Your down payment, existing debt, credit, property taxes, strata fees, mortgage rate and amortization can all change how much you qualify to borrow. How Much Income Do You Need to Buy a Home in Victoria? Here is a useful starting point. These examples assume: 20% down payment 25-year amortization No significant additional monthly debt An illustrative 4.09% mortgage rate Qualification at approximately 6.09% under Canada's mortgage stress test Property taxes and heating costs included 50% of estimated strata fees included where applicable Purchase Price Example Property Type Approx. Household Income Needed $550,000 Condo $105,000 to $110,000 $750,000 Townhouse $135,000 to $145,000 $1,000,000 Detached or larger townhouse $175,000 to $185,000 $1,311,000 Victoria Core benchmark detached home Approximately $230,000 These are illustrative estimates, not mortgage pre-approvals. A lender or mortgage broker needs to review your individual financial situation. Why These Price Points Matter in Victoria The Victoria Real Estate Board reported that the July 2026 benchmark price for a condominium in the Victoria Core was $548,600. For a single-family home in the Victoria Core, the benchmark was considerably higher at $1,311,000. That creates a large affordability gap between property types. A buyer who qualifies comfortably for a condo may need significantly more household income, a larger down payment or additional equity to move into a detached home in the Victoria Core. It is also why looking outside the Core can change the equation. Langford, Colwood, View Royal, Sooke and other Greater Victoria communities may provide different property types at the same budget. How Does the Mortgage Stress Test Affect What You Can Afford? Canadian buyers generally cannot qualify based only on the mortgage rate they will actually pay. Federally regulated lenders use a mortgage stress test. The qualifying rate is currently the greater of: Your mortgage contract rate plus 2% 5.25% For example, if your mortgage rate were 4.09%, you could be required to qualify as though the rate were approximately 6.09%. That difference can significantly affect purchasing power. At the time of writing in August 2026, advertised five-year fixed mortgage rates in BC were available around 4.09%, although the rate available to an individual borrower can be different. How Much of Your Income Can Go Toward Housing? Mortgage lenders look closely at debt-service ratios. The Financial Consumer Agency of Canada explains that total monthly housing costs generally should not exceed 39% of gross household income. Housing costs can include: Mortgage principal and interest Property taxes Heating 50% of condominium fees, when applicable Your overall debt load generally should not exceed 44% of gross income. That calculation can also include car payments, credit cards, lines of credit, student loans and other obligations. This is why two households earning $150,000 per year may qualify for very different mortgage amounts. How Much Income Might You Need for a $550,000 Condo in Victoria? With 20% down, a $550,000 condo would leave an approximately $440,000 mortgage. Using the assumptions above, a household may need roughly $105,000 to $110,000 in gross annual income. However, strata fees matter. A condo with a $350 monthly strata fee will affect qualification differently from a similar condo with a $750 fee because lenders generally include 50% of the strata fee in the housing-cost calculation. That is one reason purchase price alone does not tell you which condo is actually more affordable. Related: Why Monthly Payment Matters More Than Purchase Price How Much Income Might You Need for a $750,000 Home? At $750,000 with 20% down, the mortgage would be approximately $600,000. Under our example assumptions, a household income around $135,000 to $145,000 could be required. At this price point, buyers may be comparing: Townhouses in Victoria or Saanich Newer townhomes in the Westshore Older detached homes in some Greater Victoria areas Larger condos in central locations The important question becomes less about your maximum approval and more about where that budget creates the best combination of home, location and monthly cost. How Much Income Might You Need for a $1 Million Home in Victoria? With a 20% down payment, a $1 million purchase leaves an $800,000 mortgage. Using our assumptions, the approximate household income requirement rises to around $175,000 to $185,000. Existing debt can push that number considerably higher. For example, a car payment or large line-of-credit balance reduces the amount of income available for housing under a lender's debt-service calculation. On the other hand, a larger down payment can reduce the mortgage and therefore reduce the income needed to qualify. How Much Income Do You Need for the Benchmark Victoria Detached Home? The July 2026 MLS® HPI benchmark value for a single-family home in the Victoria Core was $1,311,000. With 20% down, that would mean a mortgage of approximately $1.05 million before other considerations. Under the same illustrative assumptions, household income could need to be around $230,000 per year. That number helps explain why many Greater Victoria buyers are adjusting one or more parts of their search: Looking farther from the Victoria Core Choosing a townhouse instead of detached Increasing their down payment Buying with a partner Considering a property with a secondary suite Choosing a smaller or older home Prioritizing monthly affordability over maximum purchase price Does a Bigger Down Payment Reduce the Income You Need? Yes. The less money you borrow, the smaller the mortgage payment used in your debt-service calculation. For example, a buyer purchasing an $800,000 property with $300,000 down has a very different qualification profile from someone purchasing the same property with $100,000 down. A larger down payment can therefore be just as important as household income when determining purchasing power. It is also important to remember that 20% is not always the minimum required down payment. For insured mortgages, Canada's minimum down payment rules currently start at 5% on the first $500,000 and 10% on the portion between $500,000 and $1.5 million. Homes priced at $1.5 million or more require at least 20% down. Can Two Buyers Combine Their Income? Yes. Mortgage qualification generally considers the combined qualifying income of the borrowers applying for the mortgage. This is why household income is often more useful than individual income when discussing Victoria affordability. A couple earning $90,000 each has a household income of $180,000, but their actual buying power will still depend on debts, credit, down payment and the specific property. Does Buying a Home With a Suite Help You Qualify? Potentially. Depending on the property and lender, some rental income from a legal or eligible secondary suite may be considered during mortgage qualification. CMHC provides methods for incorporating rental income into debt-service calculations, although the amount and treatment depend on the mortgage and property. This can make suite properties particularly important for some Greater Victoria buyers. However, buyers should confirm the suite's status and speak with their mortgage professional before assuming a certain amount of rent will be included. Pre-Approval and Comfortable Budget Are Not the Same Thing There is another number buyers should calculate: How much do you actually want to spend each month? A lender may approve you for a certain purchase price. That does not automatically mean spending the maximum will fit comfortably with your lifestyle. Remember to account for costs beyond the mortgage, including: Property taxes Home insurance Strata fees Utilities Maintenance Repairs Parking Property Transfer Tax Legal fees Moving costs Our guide to Beyond the Mortgage: Hidden Costs Buyers Forget to Budget For looks more closely at these expenses. The income needed to buy a home in Victoria is therefore only the first question. The better question is: What purchase price allows you to own the right home while still feeling comfortable financially? Frequently Asked Questions Can you buy a home in Victoria with a $100,000 household income? Potentially. Depending on your down payment, debt and other expenses, a household earning around $100,000 may be able to qualify for some condos or lower-priced properties in Greater Victoria. A mortgage pre-approval will provide a more accurate budget. Is $150,000 household income enough to buy in Victoria? It can be. Under the assumptions used in this article, a household earning around $150,000 could potentially consider properties around the mid-$700,000 range or higher, depending heavily on down payment, debt and property expenses. How much income do you need for a $1 million home in Victoria? With 20% down, no significant debt and the assumptions used above, approximately $175,000 to $185,000 in household income may be required. Do strata fees affect mortgage qualification? Yes. Lenders generally include 50% of condo fees when calculating housing costs for debt-service purposes. Find Out What Your Budget Actually Buys in Greater Victoria A pre-approval tells you how much you may be able to borrow. The next step is understanding what that budget buys in Victoria, Saanich, Langford, Colwood, View Royal and the surrounding communities. If you know your approximate purchase price, we can compare current listings and recent sales across Greater Victoria to show you where your budget goes further, which property types fit and what compromises may actually be worth making. Liam Grigg, 5-Star Review, via Google “The real estate market felt daunting, especially when it was our first time entering it. But, working with Scott made the whole process so much easier. He was really excellent at asking questions, showing us a variety of places, and helping us narrow down exactly what we were looking for. Scott was flexible, never pushy, and I really felt supported by him throughout! He made a big difference in helping us find THE place and we couldn’t do it without him. I can’t wait to work with Scott again in the future.” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.” The mortgage and income examples in this article are for general educational purposes only and are not financial or lending advice. Mortgage qualification varies by lender, borrower and property. Speak with a qualified mortgage professional for advice specific to your circumstances.
Read more
The Victoria real estate market in August 2026 is entering the second half of summer with plenty of inventory, steady buyer activity, and more room for negotiation in certain parts of the market. July gave us a useful starting point. A total of 673 properties sold across the Victoria Real Estate Board region, while 3,847 active listings remained available at the end of the month. Sales slowed slightly from June, but buyers remained active. So, what could August bring? The most likely scenario is not a dramatic market shift. Instead, we expect many of the trends seen through early summer to continue: buyers remaining selective, inventory gradually tightening, and properly priced homes continuing to outperform listings that miss the market. August Market Outlook at a Glance Based on July's market conditions, August could bring: Slightly fewer new listings as summer continues Continued selection for buyers across many property types More negotiation opportunities on homes that have been sitting Stronger activity around well-priced and well-presented properties Continued competition among condo sellers Relatively stable financing conditions heading into September August is also likely to remain highly dependent on the individual neighbourhood, property type, and price range. Inventory Could Begin to Tighten One number worth watching closely is inventory. Greater Victoria ended July with 3,847 active listings, down from the 4,054 listings available at the end of June. That does not mean buyers are suddenly running out of options. However, it may signal the beginning of the normal late-summer shift as fewer homeowners choose to launch listings during vacation season. If new listings slow while buyers remain active, some of the best properties could face stronger competition. For buyers waiting for significantly more selection later in August, there is no guarantee that will happen. Buyers May Continue to Have Negotiating Room More inventory has changed the way many buyers approach the market. Rather than feeling pressure to make an offer simply because a suitable home becomes available, buyers can often compare multiple properties and determine where the strongest value exists. That can create opportunities to negotiate beyond the purchase price, including: Possession dates Included items Repairs Subject periods Deposits Closing timelines However, negotiation power depends heavily on the property. A home that has been sitting for several weeks with limited activity may offer considerably more flexibility than a well-priced property that has just reached the market. Internal link: What Buyers Should Negotiate Beyond the Purchase Price The Best Homes Could Still Sell Quickly More inventory does not automatically mean every home will sit on the market. One of the clearest patterns we continue to see is the difference between properties that are positioned properly and those that are not. Buyers have more choices, which means they can quickly compare price, condition, location, layout, and overall value. Homes that check several of those boxes can still generate strong interest. Meanwhile, an overpriced property may sit even when similar homes nearby are selling. Condo Sellers May Face More Competition The condo market remains one area worth watching closely in August. July saw 209 condo sales, down 7.1% from July 2025. By comparison, single-family home sales increased year over year. That difference does not mean condos are performing poorly everywhere. Instead, buyers often have more comparable options available within the same building, neighbourhood, or price range. For condo sellers, small differences can matter. Floor plan, orientation, parking, storage, strata condition, fees, building reputation, and asking price can all influence which unit a buyer chooses. Internal link: Why Condos Are Facing More Competition in Victoria Right Now Prices Are Likely to Remain Relatively Stable The Victoria Core benchmark price for a single-family home was $1,311,000 in July, down from $1,326,500 in June. The benchmark condo price reached $548,600, compared with $549,200 in June. Those movements point toward a market experiencing some price pressure rather than a sharp correction. For August, buyers and sellers should pay more attention to recent comparable sales than broad regional headlines. Greater Victoria is made up of many smaller markets. A detached home in Saanich East can behave differently from a condo in downtown Victoria or a townhouse in Langford. Interest Rates Should Provide Some Stability Financing will continue to influence buyer confidence. The Bank of Canada held its policy interest rate at 2.25% on July 15, and there is no scheduled rate announcement during August. The next decision is scheduled for September 2, 2026. That does not mean mortgage rates cannot change during August, since fixed mortgage rates are influenced by bond markets rather than directly following the Bank of Canada overnight rate. Still, the absence of a Bank of Canada decision during the month removes one potential source of uncertainty for buyers actively shopping now. What August Means for Buyers August could be a useful window for buyers who are prepared but patient. There is still enough inventory in many parts of Greater Victoria to compare options, while some sellers who listed earlier in the summer may become more open to negotiating. The key is separating a genuine opportunity from a property that is simply priced poorly. Before making an offer, look at: Recent comparable sales Current competing listings Days on market Previous price adjustments Property condition Monthly ownership costs Potential upcoming repairs Long-term resale considerations The goal is not simply to get a discount. It is to buy the right property at terms that make sense. What August Means for Sellers For sellers, August is less about waiting for the market to do the work and more about positioning your property correctly. Buyers currently have enough selection to recognize when something feels overpriced. A strong August listing strategy should consider the homes currently competing for the same buyer, not simply what similar properties sold for several months ago. Presentation also matters. When buyers have choices, photography, condition, floor plan, maintenance, staging, and pricing all contribute to the first impression. Should You Buy or Sell in August? There is no universal answer. August may make sense for a buyer who finds the right property and has room to negotiate. It may also be a strong time for a seller whose home faces limited direct competition. For someone with flexibility, waiting for the fall market may offer different opportunities as more buyers and sellers return after summer. The better question is not whether August is a good month for real estate. It is whether current conditions are favourable for your particular property, price range, neighbourhood, and goals. Internal link: Should Victoria Buyers Act Now or Wait for the Fall Market? Planning a Move This August? If you are considering buying or selling in Greater Victoria this month, we can look beyond the regional numbers and break down what is happening in your specific market. Whether you are comparing listings, deciding when to make an offer, or trying to determine how your home should be positioned against current competition, having current neighbourhood-level information can make the decision much clearer. Darcy M., 5-Star Review, via Google ⭐⭐⭐⭐⭐ “I highly recommend the Faber Group and particularly Zach Parsons to anyone looking to buy or sell a home in the Victoria area. Over the past year, Zach has helped my wife and I purchase two homes, and both experiences were exceptional from start to finish. Zach is obviously knowledgeable about the Greater Victoria area, and his knowledge of the Victoria real estate market is a testament to dedication to his job and his clients." Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.”
Read more
The Victoria real estate market in July 2026 continued to give buyers plenty of choice while still producing a solid level of sales activity. A total of 673 properties sold across the Victoria Real Estate Board region in July, just 1% fewer than July 2025 and 6.4% fewer than June. At the same time, 3,847 active listings remained on the market at month-end - 3.9% more than one year earlier. (Victoria Real Estate Board) The takeaway is not that Greater Victoria has suddenly become a slow market. Instead, buyers have more options, sellers have more competition, and individual properties are behaving very differently depending on location, property type, condition, and price. July 2026 Market at a Glance According to the Victoria Real Estate Board: 673 total sales - down 1% year over year 331 single-family home sales - up 4.1% year over year 209 condo sales - down 7.1% year over year 82 townhouse sales - down 15.5% year over year 3,847 active listings - up 3.9% year over year, but down 5.1% from June Victoria Core single-family benchmark: $1,311,000 Victoria Core condo benchmark: $548,600 Victoria Core townhouse benchmark: $857,300 VREB also noted that July sales finished above the five-year average for the month, despite the greater amount of inventory available to buyers. (Victoria Real Estate Board) More Choice Is Changing Buyer Behaviour The biggest story continues to be selection. While active inventory eased from June, buyers still had more properties available than they did at the same point last year. That gives many buyers more time to compare homes rather than feeling pressured to act immediately. However, more inventory does not mean every seller is highly negotiable. Well-priced homes in desirable locations can still attract attention quickly. The difference is that buyers now have more alternatives when a property feels overpriced, needs substantial work, or does not compare favourably with competing listings. This is especially noticeable in the condo market. Condo sales fell 7.1% from July 2025, while detached home sales actually increased 4.1%. That difference reinforces why looking at Greater Victoria as one single market can be misleading. (Victoria Real Estate Board) For a closer look at this segment, read Why Condos Are Facing More Competition in Victoria Right Now. Read the condo market article Prices Continued to Soften in the Victoria Core The MLS® HPI benchmark for a single-family home in the Victoria Core reached $1,311,000 in July, down 2.8% from $1,348,400 one year earlier and down from $1,326,500 in June. For condos, the July benchmark was $548,600, down 2.2% year over year and only slightly below June's $549,200 benchmark. (Victoria Real Estate Board) These numbers suggest some price pressure, but they should not be interpreted as meaning every home has dropped by the same amount. A renovated family home in Saanich, a downtown condo, an Oak Bay character home, and a newer Langford townhouse can all face very different levels of competition. That is why understanding your specific micro-market matters more than relying on one regional number. Why Greater Victoria Real Estate Is So Micro-Market Specific What July's Market Means for Buyers For buyers, the Victoria real estate market in July 2026 offered something valuable: time to compare. In many segments, buyers can look more closely at: Recent comparable sales Competing active listings Property condition and upcoming maintenance Strata documents and financials Monthly ownership costs Days on market Price reductions Offer terms and possession dates Long-term resale potential The opportunity is not simply to negotiate the lowest price. It is to use the additional selection to find the property offering the strongest combination of price, condition, location, and long-term fit. What July's Market Means for Sellers For sellers, additional inventory means your home needs a clear reason for buyers to choose it. Pricing based solely on what a neighbour sold for six months ago can create problems. Today's buyers are comparing your property with what else they can purchase right now. Strong results are still possible, but three factors matter considerably: 1. Pricing Your asking price needs to reflect current competing inventory and recent sales. 2. Presentation When buyers have several options, condition, photography, maintenance, layout, cleanliness, and overall presentation can influence which homes make the shortlist. 3. Positioning Every property has different strengths. The goal is to understand which buyer is most likely to value those strengths and build the marketing strategy around them. The Bottom Line July was not an inactive month. 673 sales and activity above the five-year July average show that buyers are still making moves. What has changed is how much choice they have while making those decisions. (Victoria Real Estate Board) For buyers, that can create better opportunities to compare, complete due diligence, and make thoughtful decisions. For sellers, it raises the importance of competitive pricing and strong presentation from the moment the property reaches the market. Most importantly, Greater Victoria remains a collection of individual micro-markets. Whether conditions favour you depends far more on your neighbourhood, property type, price range, and competition than on a single regional headline. Wondering What July's Market Means for Your Move? If you are considering buying or selling in Greater Victoria, we can break the July numbers down to the level that actually matters - your neighbourhood, property type, price range, and current competition. Contact Faber Real Estate Group for a current market analysis and a strategy based on the homes buyers and sellers are competing with today. Nicholas D., 5-Star Review, via Google ⭐⭐⭐⭐⭐ “Scott is an awesome realtor and real estate advisor. He got me all the information I needed incredibly quick and helped me make an informed buying decision. Couldn’t have done it without him and 10/10 will be recommending him to my friends and family! There are thousands of realtors on the island, but Scott and his team are by far the best” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.” Market statistics sourced from the Victoria Real Estate Board's August 4, 2026 July market report. VREB cautions that market statistics show broader trends and do not establish the value of an individual property. (Victoria Real Estate Board)
Read more
When buyers compare homes, they usually focus on price, location, square footage, and condition. However, home orientation matters more than many buyers realize because it can affect natural light, indoor temperature, outdoor space, privacy, and how the home feels throughout the day. Two nearly identical homes can offer very different living experiences simply because one faces a different direction. Orientation is not necessarily something buyers should rank above every other feature. Still, understanding it can help explain why one home feels brighter, cooler, warmer, or more inviting than another. The Short Answer Home orientation affects how sunlight moves through a property throughout the day. Generally: East-facing spaces receive more morning sun West-facing spaces receive stronger afternoon and evening sun South-facing spaces tend to receive more direct sunlight throughout the day North-facing spaces often receive softer, more indirect light However, orientation is only part of the picture. Trees, neighbouring buildings, floor level, window placement, balconies, roof overhangs, and surrounding terrain can all change how much sunlight actually reaches a home. South-Facing Does Not Automatically Mean Better South-facing exposure is often treated as a premium feature because it can provide strong natural light for much of the day. For some buyers, that is exactly what they want. A bright living room can feel more open, while a sunny patio or backyard may become more usable during cooler months. However, more sunlight can also mean more heat during the summer. Large south-facing windows may increase indoor temperatures, particularly if the home has limited shading or no air conditioning. Therefore, the better question is not whether south-facing is best. It is whether that exposure fits the way you want to live. East-Facing Homes Can Be Great for Morning Light East-facing rooms receive their strongest light earlier in the day. That can work particularly well for kitchens, breakfast areas, bedrooms, or patios used in the morning. By afternoon, those spaces may become cooler and more shaded. As a result, east exposure can appeal to buyers who enjoy bright mornings but prefer less intense afternoon heat. On the other hand, someone who spends most of the day away from home may rarely enjoy the strongest natural light the property receives. Lifestyle matters just as much as direction. West-Facing Exposure Can Change the Evening Experience West-facing homes receive more afternoon and evening sun. For buyers who spend evenings on a balcony, patio, or deck, that can be a significant lifestyle benefit. It can also make living spaces feel brighter later in the day. However, west exposure may bring more heat during summer afternoons, especially in condos with large glass walls or limited airflow. Before deciding whether that is a positive or negative, consider how the space will be used and whether the home has blinds, air conditioning, exterior shading, or good ventilation. North-Facing Does Not Mean Dark North-facing properties are sometimes dismissed too quickly. Although they may receive less direct sunlight, they can still have excellent natural light. Large windows, higher ceilings, an open layout, lighter interior finishes, and fewer obstructions can make a north-facing home feel bright. Meanwhile, the softer light can also reduce glare and overheating. This is particularly useful for home offices, artwork, or rooms where consistent light is more desirable than strong direct sun. In other words, direction alone does not determine whether a home feels bright. Orientation Matters Even More in Condos For condo buyers, orientation can have an outsized effect because the unit may only have windows on one or two sides. A corner unit with exposure in multiple directions can receive light at different times of day. By comparison, an interior unit may depend almost entirely on one exposure. Floor level matters too. A south-facing condo on a lower floor could receive less sunlight if another building sits directly across from it. Meanwhile, a north-facing unit higher in the building may have wide-open views and excellent natural light. That is why buyers should evaluate the actual unit rather than relying on the compass direction alone. Our article on Why Floor Plan Matters More Than Square Footage looks at another factor that can dramatically change how a condo or home feels despite what the listing specifications say. Think About Outdoor Space Too Orientation matters outside the home as well. A backyard, balcony, patio, or deck can feel completely different depending on when it receives sunlight. Consider when you expect to use the space. Morning coffee might make east exposure appealing. Evening dinners may make west exposure more attractive. Meanwhile, buyers who enjoy gardening may care about how much direct sunlight reaches different parts of the property throughout the day. A large outdoor space is valuable, but its orientation can determine how often you actually want to use it. Trees and Nearby Buildings Can Matter More Than Direction Compass direction should never be considered in isolation. A south-facing backyard surrounded by mature trees may receive less direct sunlight than expected. Similarly, a condo facing west could have most of its afternoon sun blocked by another tower. Before buying, look at: Nearby buildings Mature trees Hills and terrain Balcony overhangs Window size Floor level Seasonal sun angles Future development nearby These details can have just as much impact as the direction listed on a floor plan. Consider Future Development Today's view and sunlight may not always remain the same. A vacant lot, surface parking area, or low-rise building nearby could eventually be redeveloped. For condo buyers in particular, future construction could affect views, privacy, natural light, and the feel of an outdoor space. That does not mean buyers should avoid areas experiencing development. Instead, it is another reason to understand the surroundings before making a decision. Orientation Can Affect Privacy Windows and outdoor spaces do more than bring in sunlight. They also determine what you look toward. A balcony facing an open park may feel very different from one facing directly into another building. Likewise, bedroom windows that overlook neighbouring homes may require blinds more often, reducing some of the natural light buyers expected to enjoy. Therefore, orientation should be considered alongside sightlines and privacy. Visit at Different Times of Day When Possible A home can feel very different at 10:00 a.m. than it does at 5:00 p.m. If orientation is important to you, a second viewing at another time of day can provide useful information. Notice: Which rooms receive direct sunlight Where glare appears Whether the home feels warm How bright interior rooms are How much privacy you have Whether the patio or balcony feels comfortable Photos and listing descriptions cannot always capture those differences. Seeing the property at another time can. Could Orientation Affect Resale? Orientation can influence resale, but it should not be viewed as a simple formula. Some buyers actively seek south-facing outdoor space or west-facing views. Others prioritize cooler rooms, privacy, or morning light. As a result, desirable orientation depends partly on the property itself and the buyer pool. A strong view, functional layout, useful outdoor space, natural light, and privacy can all strengthen appeal. Orientation contributes to those features, but rarely acts alone. Compare How the Home Actually Feels When home orientation matters to your decision, use the compass direction as a starting point rather than the conclusion. Ask: When Will We Be Home? Morning, daytime, and evening routines can change which exposure feels best. Which Rooms Receive the Best Light? A sunny secondary bedroom may matter less if the living room stays dark all day. Will the Home Get Too Warm? Think about glazing, shading, airflow, and cooling. Does the Outdoor Space Work When We Would Use It? A patio's size only tells part of the story. What Surrounds the Property? Nearby buildings, trees, and future development may alter light and privacy. Final Thoughts Home orientation may seem like a minor detail when you first start looking at properties. In reality, it can influence how the home feels every day. Natural light, temperature, outdoor usability, privacy, and even furniture placement can all be affected by exposure. Still, there is no single direction that works best for every buyer. The right orientation depends on the property, the surroundings, and the way you plan to live in the home. When comparing two otherwise similar properties, paying attention to where the sun comes from may reveal a difference that square footage and listing photos never will. Considering two homes with different exposures? Faber Real Estate Group can help you compare orientation, layout, surroundings, future development, and the practical details that can affect how each property feels long after the showing is over. Michael F., 5-Star Review, via Google “Cal and Scott exceeded our expectations in every way. They were always available to answer our questions and address any concerns immediately, providing exceptional support throughout the entire process. Their dedication and expertise made the selling and buying experience seamless and stress-free.” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.”
Read more
When comparing homes, buyers naturally look at square footage. However, floor plan matters more than square footage when the goal is finding a home that actually works for everyday life. Two homes can have nearly identical square footage and feel completely different. One may have open living areas, useful storage, well-sized bedrooms, and very little wasted space. Meanwhile, the other may lose valuable square footage to hallways, awkward corners, oversized entrances, or rooms that are difficult to furnish. Square footage tells you how much space exists. The floor plan tells you how useful that space actually is. The Short Answer A well-designed smaller home can feel more functional than a larger home with an inefficient layout. When comparing floor plans, consider: How much space is actually usable Bedroom size and placement Storage Hallways and circulation space Kitchen functionality Furniture placement Natural light Privacy between rooms Flexibility for future needs Resale appeal Instead of asking only, “How many square feet is it?” ask, “How well does this home use the square footage it has?” Not All Square Footage Works the Same Imagine two condos that are both 900 square feet. The first has an open kitchen and living area, two well-proportioned bedrooms, a walk-in closet, useful entry storage, and a compact hallway. The second has a long entrance corridor, awkward corners, limited closets, and a large primary bedroom that leaves the living room feeling tight. On paper, they are the same size. In practice, they may feel completely different. That difference becomes especially important with condos and townhomes, where every square foot has to work harder. Watch for Wasted Space Some floor plans dedicate a surprising amount of space to areas that have limited everyday use. Long hallways are one example. Oversized entryways, unusual angles, dead corners, and poorly positioned doors can also reduce how much of the home feels usable. Of course, circulation space is necessary. The goal is not to eliminate hallways entirely. Instead, look at how efficiently the home connects one area to another. A 750-square-foot condo with an efficient layout may offer more practical living space than an 850-square-foot condo with significant wasted space. Room Dimensions Matter A floor plan can also reveal something the total square footage cannot: where the space actually went. For example, a larger condo may have most of its additional square footage concentrated in the primary bedroom or entrance. That extra space may not help a buyer who wants a larger living room or home office. Therefore, look beyond the total. Consider whether individual rooms can comfortably accommodate the furniture you already own or expect to use. Ask yourself: Can the bedroom fit a queen or king bed comfortably? Is there space for bedside tables? Can the living room accommodate a sofa without blocking doors? Is there a practical place for a dining table? Can a desk fit somewhere without taking over another room? These details often determine whether the home feels comfortable after move-in. Furniture Placement Can Change Everything Staging can make a home look functional. Your furniture may tell a different story. Windows, doors, fireplaces, kitchen islands, baseboard heaters, and patio entrances all affect where furniture can go. As a result, a large living room may provide surprisingly few options for placing a sofa and television. Meanwhile, a smaller rectangular living room may be much easier to furnish. Before buying, imagine the room empty. Then think about how your furniture would actually fit. Measurements can be far more useful than relying on how large a room appears during a showing. Storage Is Part of the Floor Plan Storage does not always receive enough attention during a home search. Yet storage can dramatically change how spacious a home feels. A slightly smaller property with a proper entry closet, pantry, bedroom closets, linen storage, in-suite storage, or a dedicated locker may function better than a larger home where everyday belongings need to occupy living space. This becomes even more important when moving from a detached home into a condo or townhome. The question is not simply how much space you have. It is where everything will go. Bedroom Placement Affects Privacy The location of rooms matters too. For instance, bedrooms positioned on opposite sides of a condo may work well for roommates, guests, or someone working from home. Alternatively, families with young children may prefer bedrooms closer together. Similarly, a bedroom directly beside a living room or kitchen may experience more noise than one located down a hallway. Neither arrangement is automatically better. However, the layout should fit the way you plan to use the home. Natural Light Can Change How Large a Home Feels Square footage measures floor area, but it does not measure how a room feels. Natural light can make a smaller space feel brighter and more open. Window placement, ceiling height, exposure, and sightlines through the home can all influence that feeling. By comparison, a larger home with limited windows or darker interior rooms may feel more confined. Therefore, buyers should consider both measurable space and perceived space. Both affect how enjoyable the home may be to live in. Open Concept Is Not Always Better Open layouts remain popular, but openness should not automatically be confused with functionality. An open kitchen and living room may create better flow and make a smaller home feel larger. However, some buyers value separation. A dedicated office, defined dining space, separate kitchen, or second living area may be more useful depending on the household. The better floor plan is not necessarily the most open. It is the one that creates the right balance between connection and separation for the people living there. Think About How Your Needs Could Change A good floor plan should work today. Ideally, it also offers some flexibility for tomorrow. A den might become an office, nursery, guest room, or additional storage space. Likewise, a second bedroom might serve several purposes over the years. Flexible space can become particularly valuable when moving again would be expensive or inconvenient. As a result, buyers should consider whether the home can adapt as work, family, hobbies, or lifestyle needs change. A Bigger Home Can Still Feel Smaller This is why floor plan matters more than square footage in many buying decisions. More square footage can be valuable, but only when that additional space improves how the home functions. If another 100 square feet consists mostly of hallways, oversized rooms you do not need, or awkward areas you cannot use, it may provide less value than expected. At the same time, buyers should consider the full cost of that additional space. A larger home may mean a higher purchase price, larger strata fees, more furniture, higher utilities, or increased maintenance. Our article on Why Your Monthly Payment Matters More Than the Purchase Price looks at why the overall cost of ownership deserves as much attention as the price itself. Floor Plan Can Affect Resale Too Eventually, future buyers will evaluate the layout as well. Functional floor plans tend to appeal to a broader range of people because they make everyday use easier. Common considerations include: Practical bedroom sizes Useful storage Good natural light Limited wasted space Clear furniture placement Separation between private and living areas Flexible rooms Easy access to outdoor space Buyer preferences will vary. Still, a practical layout is often easier to understand and use than one that requires compromises from the moment someone walks through the door. Compare How the Homes Live, Not Just Their Numbers When deciding between two properties, try comparing them without looking at the total square footage first. Where Would We Spend Most of Our Time? Is enough space allocated to those rooms? Where Does Everything Go? Are storage and closets adequate? Can We Furnish It Properly? Do room dimensions and wall locations work? Does the Layout Fit Our Lifestyle? Consider privacy, entertaining, working from home, children, pets, and guests. Could It Still Work in Five Years? Look for flexibility rather than only today’s needs. Once you have answered those questions, the square footage number has much more context. Final Thoughts Square footage is useful, but it should not decide which home is better. A thoughtful floor plan can make a smaller property feel comfortable, practical, and surprisingly spacious. On the other hand, inefficient design can make a larger home feel tighter than expected. That is why buyers should compare how each home actually functions. Look at the room sizes. Consider furniture placement. Check the storage. Think about natural light, privacy, and flexibility. The best home is not necessarily the one with the most square footage. It is the one that uses its space in a way that fits your life. Comparing homes with similar square footage but very different layouts? Faber Real Estate Group can help you look beyond the numbers and compare functionality, location, monthly costs, resale considerations, and the trade-offs that may matter most over the years you own the home. Nilo M., 5-Star Review, via Google “This group have a high level of commitment to help and to put thier client’s need ahead of their personal gain. They deal and engage with integrity and wisdom on how it will work for both the seller and the clients. I experienced it first hand in this crazy and difficult season. We just bought a home at Glanford area, and they are always there for us, every step of the way. They are real and can be trusted.” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.”
Read more
Should you buy now or wait until fall in Victoria? It is a reasonable question, especially when buyers are seeing more listings, hearing mixed opinions about interest rates, and wondering whether better opportunities could appear later in the year. The problem is that waiting only works when something specific is expected to improve. Fall may bring different listings and changing market conditions, but it does not guarantee lower prices, lower mortgage payments, or less competition. The Short Answer Buyers who are financially prepared, understand their monthly costs, and find the right property may have good reasons to act now. Buyers who need more time to strengthen their finances, sell another property, or clarify what they need may benefit from waiting. The decision should depend less on predicting the fall market and more on whether waiting creates a measurable advantage. What the Victoria Market Looks Like Right Now The Greater Victoria market is offering buyers more selection than it did during the low-inventory years. In June 2026: 719 properties sold across the Victoria Real Estate Board region Sales were 5.5% lower than in June 2025 There were 4,054 active listings at the end of the month Active inventory was 7.3% higher than one year earlier VREB described the market as active and balanced, with buyers generally having more time and more options to compare properties. Prices have also varied by property type. In the Victoria Core, the June benchmark was approximately $1,326,500 for a single-family home and $549,200 for a condominium. Both were slightly lower than their June 2025 benchmarks. This does not mean every property is negotiable or that prices are falling evenly across the region. Well-priced homes in desirable locations can still attract strong interest. Why Buying Now May Make Sense You Have More Properties to Compare Higher inventory can give buyers more opportunities to compare: Condition Location Layout Strata fees Parking and storage Renovation requirements Monthly ownership costs Seller motivation More listings do not automatically mean lower prices, but they can reduce the pressure to make a rushed decision. You May Have More Negotiating Room Negotiation is not limited to the purchase price. Depending on the property and seller, buyers may be able to negotiate: Subject conditions Completion and possession dates Included items Repairs Credits or adjustments Deposit timing A price that reflects the home’s condition Properties that have been sitting on the market or competing with several similar listings may give buyers more room to structure favourable terms. The Right Property Is Available Now A home that fits your budget, location, layout, and long-term plans may be more valuable than a hypothetical fall opportunity. Waiting may produce a lower-priced listing. It may also mean losing a home that is unusually well suited to your needs. The goal is not to buy quickly. It is to recognize when the right combination of property, price, and terms becomes available. Why Waiting Until Fall May Make Sense Waiting can be a smart strategy when the extra time improves your position. That may include: Increasing your down payment Paying down debt Improving your credit Confirming employment or income Selling your current home Receiving a clearer mortgage approval Narrowing your preferred neighbourhoods Building a stronger emergency fund In these situations, waiting is not an attempt to time the market. It is a way to become a more prepared buyer. Do Not Assume Mortgage Rates Will Be Lower The Bank of Canada held its policy rate at 2.25% on July 15, 2026. Its next scheduled rate announcement is September 2, 2026. The Bank also emphasized that economic and inflation uncertainty remains elevated. That means buyers should avoid building their plans around an assumed fall rate reduction. BCREA’s June mortgage outlook expected the Bank of Canada to hold its policy rate through the remainder of 2026, while noting that fixed mortgage rates remain sensitive to bond markets and global economic conditions. Rates could improve, remain similar, or move higher. A lower rate could also bring more buyers back into the market, increasing competition for desirable homes. The better approach is to calculate what you can comfortably afford under current conditions and treat any future improvement as a benefit rather than a requirement. Victoria Is Not One Real Estate Market Market timing can look very different depending on what you are buying. A downtown condo does not compete in the same market as a detached home in Saanich. A Langford townhome may face different supply and demand than a character home in Fairfield or a waterfront property on the Peninsula. Your decision should consider: Property type Price range Municipality Strata or freehold ownership Condition New construction versus resale Number of competing listings Recent comparable sales Broader statistics provide context, but the best timing decision comes from studying the specific micro-market where you plan to buy. Four Questions to Ask Before Waiting Before postponing your search until fall, ask: 1. What exactly do I expect to improve? Identify whether you are waiting for better finances, more suitable inventory, lower rates, or lower prices. 2. Is that improvement within my control? Saving more money is within your control. Predicting where home prices or mortgage rates will be in October is not. 3. What happens if conditions do not improve? Consider whether you would still buy in the fall if prices, rates, and inventory remained similar. 4. Would the right home today change my decision? If the answer is yes, it may make sense to remain active while keeping strict criteria rather than pausing your search completely. The Bottom Line Deciding whether to buy now or wait until fall in Victoria is not about choosing the perfect month. Buying now may make sense when: Your finances are ready Your monthly payment is comfortable You expect to remain in the home long enough The right property is available The price and terms reflect the current market Waiting may make sense when: Your financial position will clearly improve Your timeline is flexible Current inventory does not meet your needs You are still uncertain about location or property type Buying now would place too much pressure on your budget A strong buying decision is based on preparation, property-specific value, and personal timing - not the hope that the next season will automatically offer a better deal. Compare Buying Now With Waiting Until Fall If you are unsure whether to act now or pause your search, Faber Real Estate Group can compare current listings, recent sales, monthly ownership costs, and competition within your preferred Victoria neighbourhoods. The goal is not to push your timeline forward. It is to help you understand what waiting could improve, what it could cost, and whether the right opportunity is already available. Douha E., 5-Star Review, via Google “Finding a home can be stressful, but Scott made it easy. He was so patient with us, answered all our questions, and gave us honest advice that helped us find the perfect home. We’re thrilled with the outcome and would 100% recommend Scott to anyone looking to buy. He’s great!” Faber Real Estate Group Royal LePage Coast Capital Realty 📞 250-244-3430 📧 [email protected] ℹ️ Scott Faber Personal Real Estate Corporation ℹ️ Cal Faber Personal Real Estate Corporation Vanessa Wood, Zachary Parsons, and Sophie Taylor “Building Lasting Relationships, One Home at a Time.”
Read more